Executive Overview
The intersection of fine art and speculative finance has always been a volatile frontier. For centuries, masterpieces have served as both aesthetic triumphs and alternative asset classes, driven by prestige, the whims of the ultra-wealthy, and opaque private transactions. However, a recent strategic alliance has thrust the traditional art market directly into the mechanics of modern digital speculation.
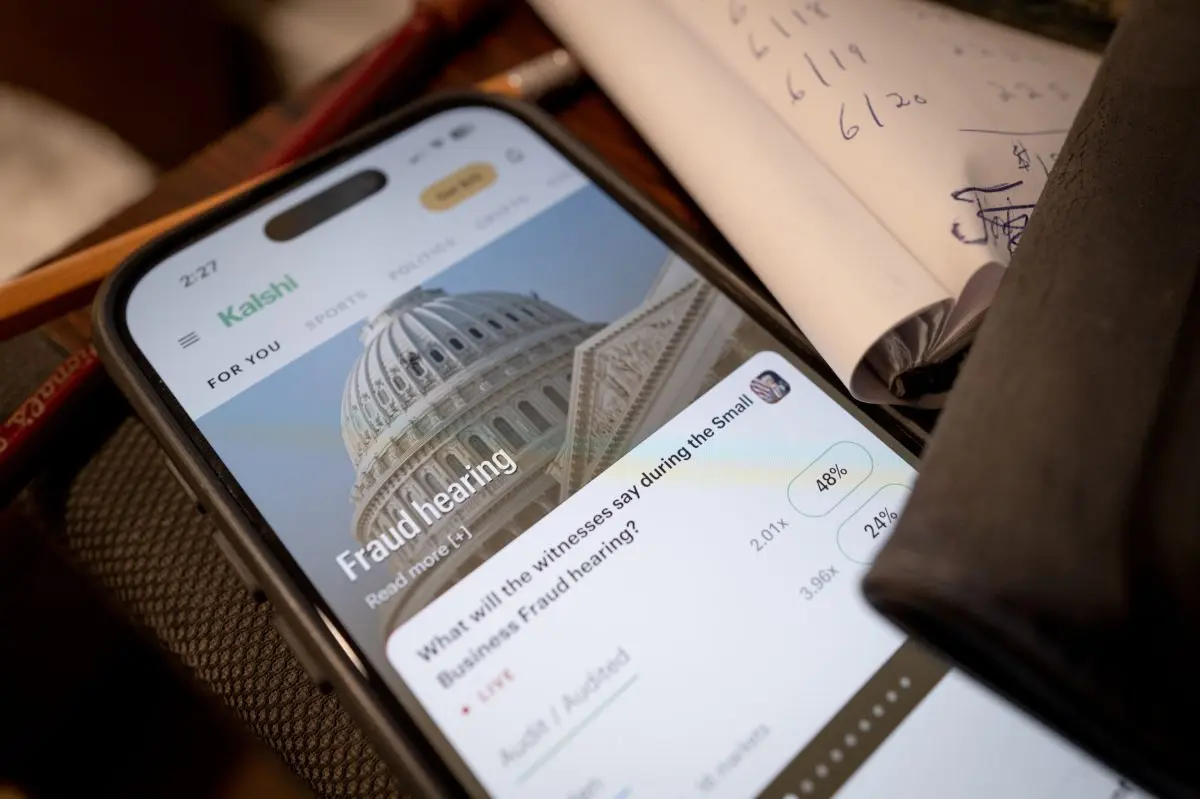
In a move that sent immediate shockwaves across the cultural and financial landscapes, Artnet announced a landmark partnership with Kalshi, the regulated financial exchange renowned for allowing users to wager on real-world events, ranging from macroeconomic indicators to national elections. Under this new agreement, Artnet will serve as Kalshi’s official art partner, assisting in the curation of prediction markets and supplying the authoritative auction data necessary to determine payouts.
This development, arriving on the heels of Artnet’s merger with online brokerage Artsy, coincides with the high-stakes New York autumn auction season. It formalizes a crossover between high-end cultural transactions and gamified betting that has been quietly brewing since Kalshi first introduced art-related contracts earlier this year. While proponents argue that prediction markets democratize engagement with the art world—offering non-collectors a way to participate in the excitement of major sales—critics, industry insiders, and online commentators have voiced deep skepticism. Concerns range from the perils of insider trading and information asymmetry to the potential for artificial market manipulation and the sheer unpredictability of high-end cultural valuation.
Read Also
As regulatory bodies, auction houses, and market participants grapple with this fusion of culture and commerce, the core question remains: Is this innovative partnership a legitimate evolution in market transparency, or is it a high-risk gamble that threatens to reduce masterworks to mere gaming chips?
Detailed Chronology
To understand the current friction between traditional art curation and digital prediction markets, it is necessary to trace the sequence of events that brought these two distinct industries into collision.
May: The Initial Foray
The foundation for the current controversy was laid earlier in the year when Kalshi first ventured into the cultural sphere, introducing art-related prediction markets. By allowing users to trade contracts on individual paintings, entire institutional or private collections, and the potential breaking of artist auction records, Kalshi signaled its intent to apply the mechanics of predictive finance to the fine art sector. At the time, major auction houses such as Christie’s and Phillips reacted with caution, noting that existing corporate compliance policies regarding material non-public information and conflicts of interest would extend to cover prediction markets. Meanwhile, competitors like Sotheby’s declined to comment.
Summer: Corporate Consolidation
The summer months brought significant structural shifts within the art media and brokerage space. Seven months prior to the Artnet-Kalshi announcement, Artnet—a premier source for auction data, analytics, and cultural journalism—announced its merger with Artsy, an online art brokerage platform. The newly combined entity was placed under the leadership of Chairman Andrew Wolff, CEO of Beowolff Capital, which had quietly secured majority stakes in both companies over the preceding year. This consolidation created a powerful digital conglomerate with unprecedented reach into both the informational and transactional sides of the global art market.
Wednesday: The Partnership Announcement
The partnership between Artnet and Kalshi was officially formalized on a Wednesday. The announcement detailed Artnet’s new role as Kalshi’s exclusive art partner. According to the agreement, Artnet will utilize its extensive Price Database to verify auction outcomes and supply the empirical benchmarks required to settle Kalshi’s prediction contracts. Crucially, the announcement emphasized a strict firewall: Artnet’s newsroom would remain entirely independent, absolved of any involvement in creating the markets or verifying betting results.
Immediate Backlash and the Fall Auction Circuit
The public reaction, particularly across digital spaces like Instagram, was swift, satirical, and largely hostile. Commentators lambasted the partnership for introducing yet another mechanism for speculation into an already strained ecosystem, with some quipping about the convenience of "misunderstanding art from anywhere" and others lamenting the creation of additional tools to "artificially inflate an artist’s market and destroy their career before they turn 30."
Despite the online pushback, the partnership timed itself directly ahead of New York’s marquee November sales. This premier auction window—featuring blue-chip works by modern and contemporary masters—provided an immediate testing ground for Kalshi’s portfolio of art-related financial instruments.
Supporting Context & Metrics
While the headlines focus on the cultural implications of betting on art, an examination of the underlying metrics reveals a stark contrast between the colossal valuations of the physical artworks and the nascent state of the prediction market itself.
Scale Disparities: Billions in Art vs. Hundreds in Bets
To contextualize the phenomenon, one must look at the volume of capital currently moving through both spheres. During the November auction cycle, works by legendary artists routinely command tens of millions of dollars. For instance, Yoshitomo Nara’s seminal 2001 painting Candy Blue Night headed to Sotheby’s with valuations soaring into the multi-millions, allowing Kalshi users to trade contracts on whether the final hammer price would cross specific thresholds, such as $6 million or $7 million. Similar contracts were made available for major pieces by Francis Bacon, Andy Warhol, and Roy Lichtenstein.
Yet, despite the multi-million-dollar valuations of the physical assets, the actual capital flowing through the prediction markets remains remarkably modest. Data from a market established for Sotheby’s Blaquier-Arrieta Collection—which carried a collective pre-sale expectation of exceeding $500 million—revealed that traders evaluated the probability of that milestone at roughly 52 percent. At the time of observation, however, that specific prediction market had attracted a mere $372 in total trading volume.
This vast disparity underscores the experimental nature of the venture. For now, Kalshi’s art markets function less as a robust alternative financial ecosystem and more as a speculative sandbox operating on the periphery of the multi-billion-dollar global art trade.
The Mechanics of Art Valuation
Industry veterans point out that the traditional art market does not behave like traditional equities or commodities. Philip Hoffman, founder and chairman of the Fine Art Group, highlights the fundamental unpredictability of the high end of the market. While lower-value, highly standardized works or commercial prints can yield relatively predictable pricing patterns based on historical data, blue-chip masterworks defy straightforward algorithmic forecasting.
Hoffman illustrates this volatility through a personal anecdote from his career, recalling an occasion when he guaranteed a Willem de Kooning painting widely anticipated to comfortably clear $10 million. When an unforeseen macroeconomic downturn caused the broader stock market to stumble, prospective bidders vanished. Hoffman was left holding the painting himself, ultimately offloading it years later for $9.7 million and absorbing a $300,000 personal loss.
This anecdote underscores a foundational reality of the art world: personal taste, historical provenance, condition reports, and the impulsive whims of ultra-high-net-worth buyers can render even the most rigorous valuations obsolete the moment the auctioneer raises the gavel.
Official Statements and Industry Perspectives
The introduction of prediction markets into the fine art ecosystem has elicited a spectrum of responses from leading market advisors, former auction specialists, and corporate entities.
Proponents: Community Engagement and Alternate Participation
Wendy Cromwell, founder of the advisory firm Cromwell Art and a former contemporary-art specialist at Sotheby’s, sees potential upside alongside legitimate concerns. From her perspective, prediction markets offer an alternative avenue for cultural engagement.
"I do think it’s a way for people to participate in the community," Cromwell observed, noting that this inclusion applies to individuals who are deeply invested in the cultural landscape, follow emerging and established artists closely, and understand market trends, even if their personal capital does not allow them to participate as physical collectors.
However, Cromwell is quick to highlight the structural vulnerabilities of the platform, particularly regarding information asymmetry.
"It’s going to be extraordinarily tempting for everybody because everyone in the art world has inside knowledge," she warned.
Skeptics: The Illusion of Predictability
Conversely, other industry leaders remain entirely unconvinced of the utility or validity of these financial instruments. Philip Hoffman dismissed the notion that prediction markets provide any tangible benefit to serious collectors. In his estimation, attempting to forecast the closing prices of major cultural assets is a fool’s errand, given the emotional and irrational nature of high-end bidding wars.
"People get carried away if they truly want it, and there is no price," Hoffman stated, reinforcing the idea that trophy-asset acquisition is governed by psychological impulses that defy quantitative modeling.
Echoing this sentiment, Wendy Cromwell cautioned against treating prediction markets as authoritative barometers of cultural or monetary value.
"I think it’s a fool’s game to listen to prediction markets," she concluded. "If you’re spending lots and lots of money, you should do your own research and have your own convictions about what you want to spend."
Future Outlook & Critical Concerns
As the partnership between Artnet and Kalshi settles into the rhythm of the global auction calendar, several critical structural and ethical questions loom over the horizon. The long-term viability and integrity of art prediction markets will likely hinge on how these challenges are addressed.
The Information Asymmetry Dilemma
The fine art market has historically operated on a degree of opacity that would trigger immediate regulatory investigations in traditional public equities markets. Senior auction-house specialists routinely possess confidential data regarding how many prospective buyers are registered for a given sale. Private dealers and art advisors often maintain intimate knowledge of who desires a specific painting, how aggressively they pursue it, and the maximum ceiling of their budget. Furthermore, financial guarantors frequently hold direct stakes in the performance of a work long before it crosses the auction block.
This creates a severe information imbalance within a prediction market. A casual retail trader relying solely on public auction estimates and social media sentiment operates at a profound disadvantage against industry insiders who may possess confidential insights regarding absentee bids, private guarantees, or unpublicized expressions of interest.
While Kalshi enforces explicit rules prohibiting material non-public information trading—and bars insiders such as consignors, bidders, guarantors, and auction staff from participating in relevant contracts—enforcing these restrictions within a global industry built on discretion presents a monumental compliance challenge.
The Risk of Feedback Loops and Market Manipulation
Perhaps the most troubling theoretical implication of art prediction markets is their potential to actively influence the physical auctions they track. Observers have raised concerns about the emergence of a speculative feedback loop.
Consider a scenario where overwhelming bullish sentiment on a prediction platform drives projected prices sky-high. A prospective buyer attending a live auction, influenced by the public narrative that a particular picture is guaranteed to shatter its pre-sale estimate, might second-guess their independent advisor’s valuation and overextend their financial reach. Conversely, bad actors or speculative syndicates could attempt to manipulate prediction markets to artificially inflate or depress the perceived market value of an artist’s upcoming inventory, weaponizing public sentiment for private financial gain.
Experiment vs. Established Asset Class
Despite these profound concerns, the immediate reality remains tempered by scale. With modest trading volumes juxtaposed against billion-dollar auction receipts, Kalshi’s art-related offerings function primarily as a novel financial experiment rather than a dominant force in wealth management.
Artnet’s integration adds a layer of empirical legitimacy by anchoring the verification process to established transactional data, but the fundamental friction between the subjective beauty of art and the cold calculus of betting exchanges remains unresolved. Whether collectors will ultimately utilize these contracts to hedge their portfolio exposure—or if the initiative will remain a fleeting novelty ridiculed on social media—will be decided as the market matures through subsequent auction cycles. For now, the canvas remains mounted in the gallery, while the casino floor hums quietly in the digital background.

Comments
Facebook App ID not configured. Please add it in the Customizer.